Tag: modified car insurance uk

  • Modified Car Insurance in the UK Is Getting Harder to Find, Here’s Why and What to Do About It

    Modified Car Insurance in the UK Is Getting Harder to Find, Here’s Why and What to Do About It

    Right, let’s not sugarcoat this. Modified car insurance in the UK is becoming a proper headache, and it’s only getting worse in 2026. Specialist insurers who used to wave through stage-one remaps and aftermarket exhausts without blinking are now treating your build like it’s a financial hand grenade. I’ve spoken to lads at meets across the country who’ve had policies declined, voided mid-term, or priced so high they’d rather park the car in the garage and cry. So what’s actually going on?
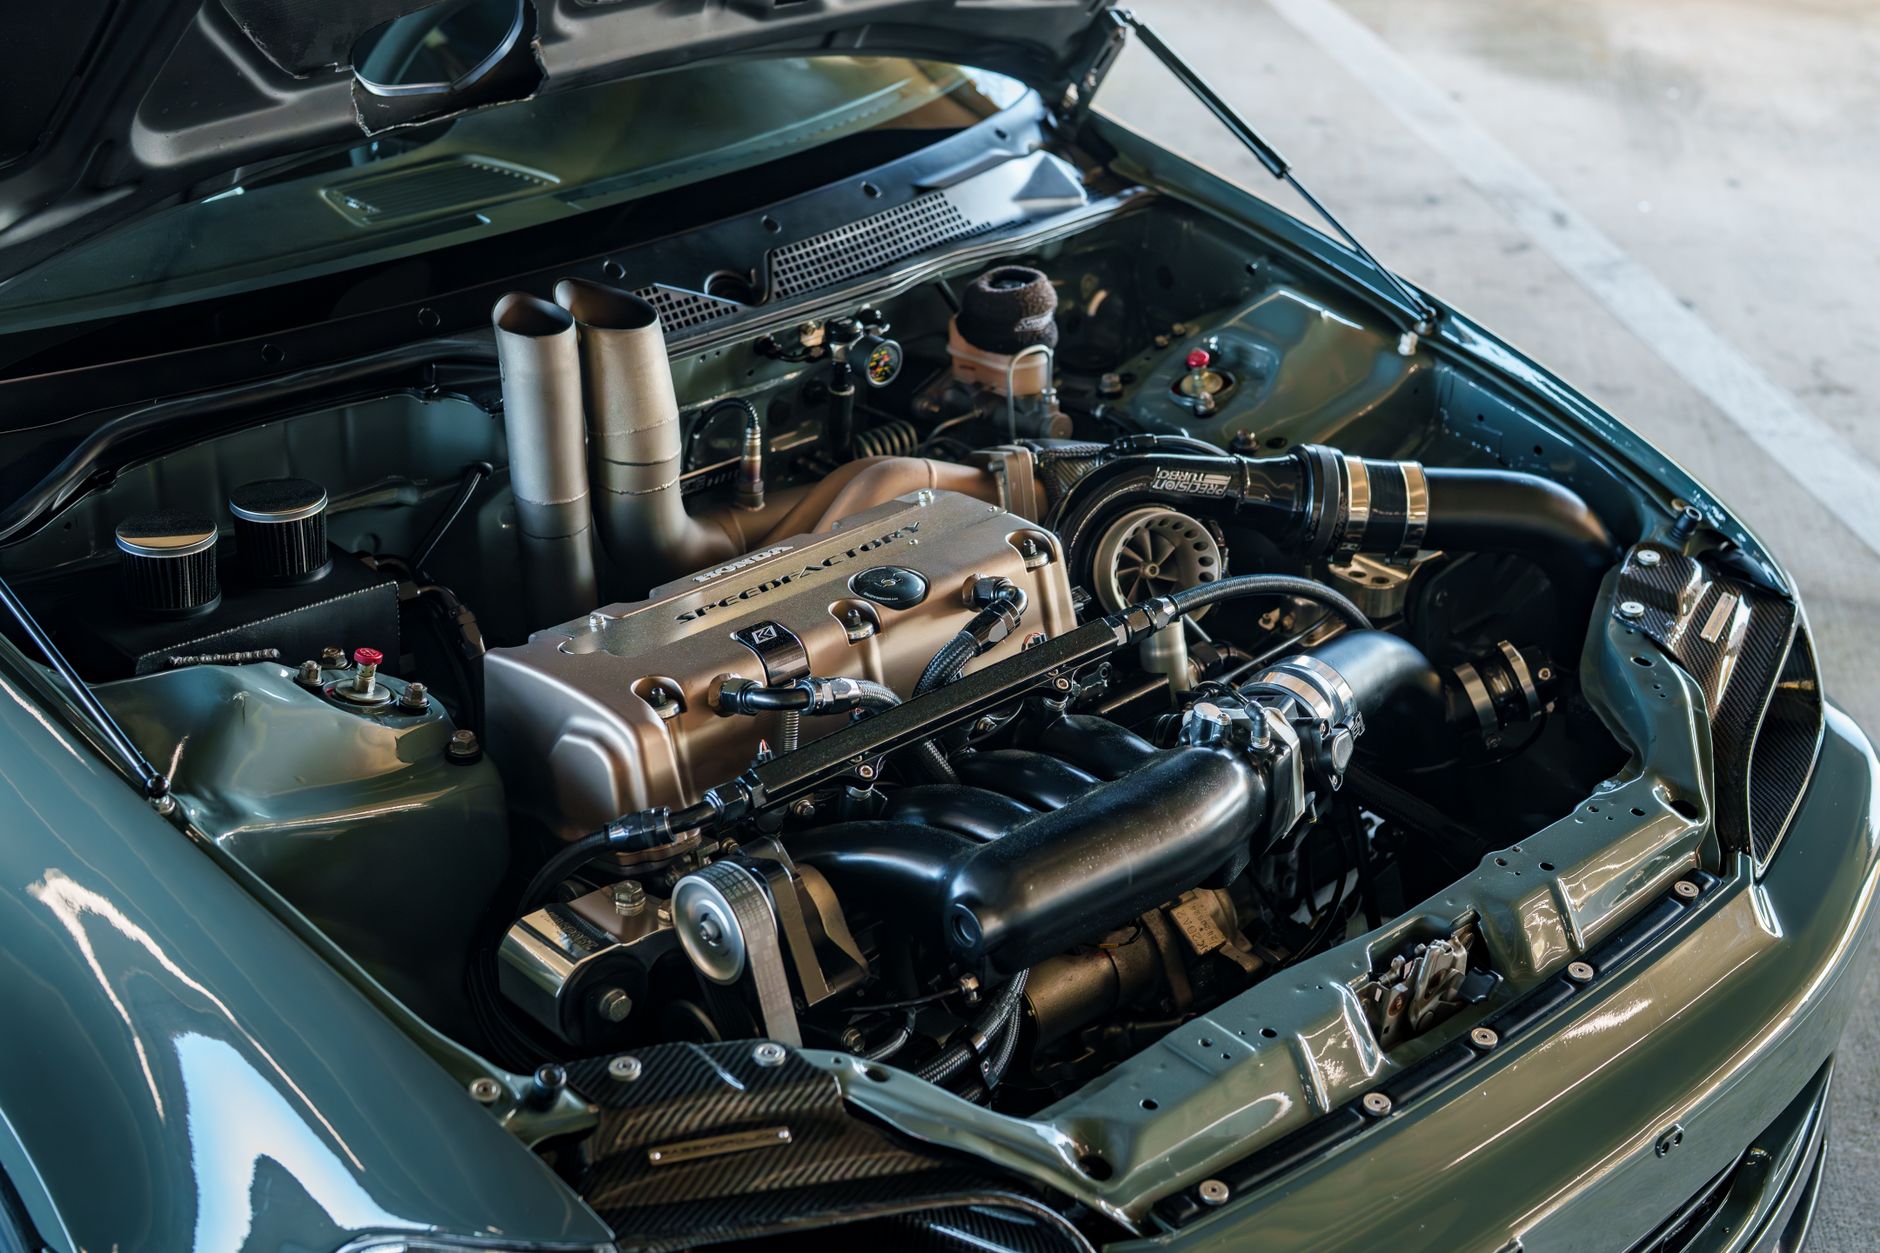
    Modified car engine bay representing the kind of build that makes modified car insurance UK a complex challenge
    Photo by astesmedia on Pexels

    The short version: claims data caught up with the enthusiasm. Between rising repair costs, increased theft of modified vehicles, and a wave of young drivers binning modified hot hatches on roundabouts, underwriters have started reading the room. The result is tighter criteria across the board, more outright refusals for certain modification categories, and premiums that’ll make your eyes water. But there’s still a path through this mess if you know what you’re doing.

    Why modified car insurers are pulling back in 2026

    The UK insurance market has been under serious pressure. According to the Association of British Insurers, motor claims costs hit record levels in 2024 and haven’t eased since. Labour costs at bodyshops, the price of specialist parts, and longer repair times have all hammered insurer margins. Modified cars cost more to fix. Full stop. A standard bumper on a hot hatch is one price; the same bumper with a custom aero lip, repainted in a bespoke wrap colour, and fitted with carbon fibre vents is a completely different conversation.

    Theft is the other killer. Keyless entry exploits, relay attacks, and organised gangs specifically targeting modified cars have pushed theft claims through the roof. A well-known JDM build or a Stage 2 Volkswagen Golf with £4,000 in audio and £3,000 in wheels is a target. Insurers know this, and they’re pricing accordingly. Some are walking away from certain platforms entirely.

    Which modifications are getting refused cover in 2026

    This is where it gets real. I’d say there are roughly four categories of modification that specialist insurers are increasingly refusing to touch, declining to properly rate, or simply loading so heavily that the premium becomes academic.

    Engine remaps and ECU tuning used to be relatively straightforward to declare. Now, anything beyond a manufacturer-approved or dealer map is being scrutinised hard. Stage 2 and above on certain platforms, particularly turbocharged four-cylinders, are triggering outright refusals from some underwriters. If you’ve read our honest breakdown of remapping your car in the UK, you’ll know the insurance angle was already tricky. It’s got worse.

    Suspension modifications are another flashpoint. Coilovers set below a certain ride height, air ride systems that don’t have documented proof of a legal ride height when driven on public roads, and aggressive camber setups are all raising red flags. Insurers aren’t just worried about handling, they’re worried about liability if the car is involved in a collision and a solicitor argues the suspension setup was a contributing factor.

    Wide-arch and body kit conversions are getting hit too, especially anything that increases the vehicle’s width or track without proper documentation. Aftermarket roll cages, stripped interiors for track use, and removal of safety equipment like rear seatbelts are in a similar boat. Some insurers will only touch these at all if you’ve got a motorsport-specific policy through a body like Motorsport UK.

    Turbocharged conversions and engine swaps are essentially uninsurable through most standard modified car insurers now. If you’ve dropped a different engine into your build, you’re looking at a very small pool of specialist underwriters, and the premiums reflect that scarcity.
    Modified hot hatches at a UK car meet, the kind of builds that require properly declared modified car insurance UK
    Photo by Artem Krapivin on Pexels

    How to actually get modified car insurance without being fleeced

    Here’s the thing that most people get wrong. They either declare nothing and hope for the best, which is fraud and will leave you uninsured when you need it most, or they declare everything to a standard insurer who immediately either refuses or quotes £4,000 a year. Neither of those is the move.

    The right approach is a proper specialist broker who genuinely understands the modified car scene. Brokers like Adrian Flux, Footman James, and Performance Direct exist specifically for this market. They have access to underwriters who actually know what a Stage 1 remap does to power output and risk profile, and can price it sensibly. Ring them. Speak to a human. Don’t just use a comparison site and wonder why every quote is mental.

    Document everything. Build a modification log with photos, receipts, and where relevant, dyno sheets showing power output. If you’ve used quality, reputable fabricators, the kind of outfits like Forged Chassis who specialise in proper engineered builds, make sure you can prove it. Insurers respond better to documented, professional work than to a list of eBay receipts.

    Agreed value policies are worth looking at for higher-spec builds. Rather than having an argument about market value after a total loss, you agree the car’s value upfront, including the modifications. Yes, the premium is higher. But getting paid out at standard book value on a car you’ve spent £15,000 modifying is a nightmare you don’t want.

    And declared value policies absolutely require that your MOT situation is in order. If you’ve been modifying heavily and skipped the implications, things like suspension geometry, emissions changes from a remap, or non-standard lighting, read up on what UK MOT testers are clamping down on in 2026. A failed MOT makes your insurance invalid. That’s not a small problem.

    The mileage and storage angle people overlook

    One genuinely useful lever is how and where you use the car. Agreed mileage policies, where you declare a realistic annual mileage and stick to it, can bring premiums down meaningfully. If your modified car is a weekend cruiser and a show car rather than a daily driver, say so and prove it. Insurers want to know the car isn’t doing 20,000 miles a year in commuter traffic where accident frequency goes up.

    Secure storage matters too. A modified car kept in a locked garage with a Thatcham-approved immobiliser, a tracker fitted, and a steering lock is a different risk proposition to the same car on a road outside a flat. These details shift the premium. I’ve seen quotes drop by 20 to 25 per cent just from properly evidencing security measures.

    What’s coming next for modified car insurance

    Telematics are entering this space whether the cruise scene likes it or not. Some specialist insurers are starting to offer black box or dashcam-linked policies for modified cars, using driving data to offset the risk profile of the vehicle’s modifications. If you drive sensibly most of the time, the data backs you up. If your idea of a Sunday morning is blasting every A-road in sight, maybe don’t volunteer for a telematics policy.

    The community side matters here too. Car meet culture, the growth of well-organised events on private land, detailed in our piece on how UK cruise meets are using private land legally, actually helps normalise the modified car community in the eyes of the wider public and eventually insurers. The more this scene is documented as organised and responsible, the better the long-term picture.

    Getting properly insured is not optional, and it’s not something to bodge. Sort it properly, use a specialist, and declare everything. Your build is worth protecting, do it right.

    Frequently Asked Questions

    Do I have to declare every modification to my car insurer?

    Yes, every single one. Failing to declare modifications is classed as material non-disclosure, which can void your policy entirely and leave you uninsured after a claim. Even cosmetic changes like alloy wheels or a body kit must be declared.

    Which specialist modified car insurers operate in the UK?

    Adrian Flux, Footman James, Performance Direct, and Reis are among the well-known UK specialists with access to underwriters experienced in modified vehicles. Always speak to a broker directly rather than relying solely on comparison sites, as many non-standard builds won’t show competitive quotes through aggregators.

    Will a stage 2 remap invalidate my car insurance?

    Not automatically, but you must declare it. If you don’t declare a remap and make a claim, the insurer can refuse to pay out. Some underwriters will refuse to cover Stage 2 and above, while others will load the premium. A specialist broker is your best route to finding one who will insure it properly.

    How much more expensive is modified car insurance compared to standard cover?

    It varies enormously depending on the modifications, the car, your driving history, and your age. Light modifications like alloys and a stage one map might add 20 to 40 per cent to a standard premium, while significant engine work or a full track-spec build can push premiums two to three times higher than a standard equivalent.

    Can I get agreed value insurance on a modified car in the UK?

    Yes, several specialist insurers offer agreed value policies for modified cars where you document and agree the car’s true value, including modifications, upfront. This protects you from being paid out at standard book value after a total loss. Specialist brokers like Footman James and Adrian Flux offer these policies.
  • How to Start Modifying Your Car in 2026 Without Getting Nicked or Going Broke

    How to Start Modifying Your Car in 2026 Without Getting Nicked or Going Broke

    Right, so you’ve got your first car, you’re buzzing, and you’re already on YouTube at midnight watching boost tutorials and wheel fitment videos. We’ve all been there. But before you start lobbing on a splitter and winding down the coilovers, there’s a very real conversation we need to have about what’s legal, what gets your car impounded, and how to not burn through your entire wage packet on mods that’ll fail your MOT. This guide breaks down how to modify your car legally UK style, without the lecture and without the fluff.

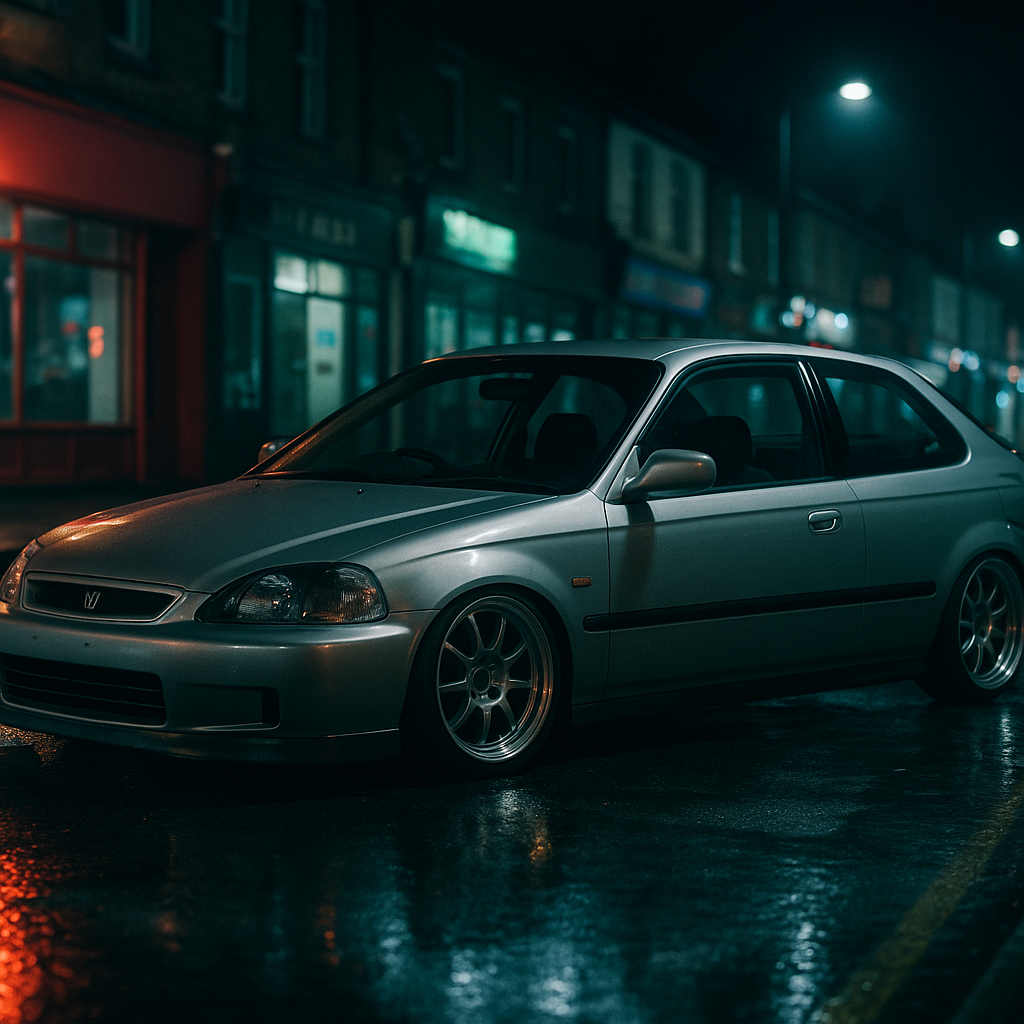
    Lowered modified Honda Civic on UK street showing how to modify your car legally UK style
    Lowered modified Honda Civic on UK street showing how to modify your car legally UK style

    Why Knowing the Law Matters Before You Touch a Bolt

    Here’s the thing nobody tells you when you’re deep in a modified car Instagram rabbit hole at 1am: the law genuinely doesn’t care how sick your build looks. If your car isn’t road-legal, you’re looking at a Section 59 warning, a potential seizure, points on your licence, or all three at once. That’s not a vibe. The police have the power under the Road Traffic Act 1988 to pull you for modifications that make your car unsafe or non-compliant, and in 2026 with the increase in ANPR cameras and dedicated roads policing units across the UK, they’re more switched on than ever.

    The good news? Most popular mods are totally fine if you do them properly. The problem is that people cut corners, buy cheap bits off dodgy marketplaces, and then act surprised when they get a prohibition notice. Don’t be that person.

    What Modifications Are Actually Road-Legal in the UK?

    Let’s get into the good stuff. These are mods that are broadly road-legal when done correctly, though always check with your insurer and the DVLA if you’re unsure about your specific setup.

    Wheels and Tyres

    Changing your wheels is one of the most visually impactful things you can do. Stick to the correct load and speed ratings, make sure the tyres aren’t rubbing on the arches at full lock, and keep the tyre width within the manufacturer’s tolerance range. Stretching tyres is a grey area and some MOT testers will fail them, so know the risks before you commit. Stick to wheels with the correct PCD and offset for your car, and you’ll be fine.

    Suspension Lowering

    Coilovers and lowering springs are legal as long as your car still meets the minimum ground clearance requirements and the handling isn’t compromised. Slamming it so low that your front lip sparks on every speed bump isn’t just dangerous, it’s an MOT failure and a guaranteed pull from any traffic officer worth their salt. A sensible 30-40mm drop on quality coilovers from brands like Eibach or KW is the sweet spot between looking tidy and staying legal.

    Exhaust Systems

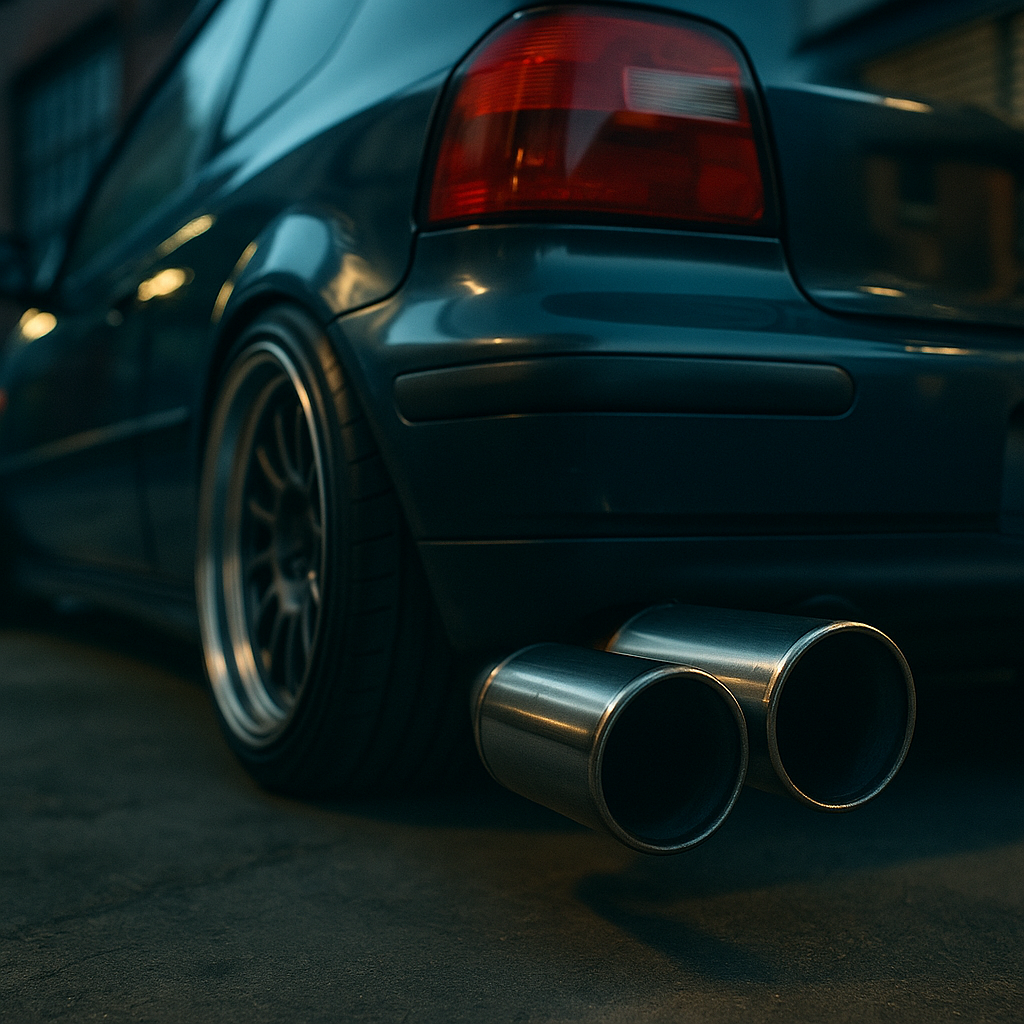
    This is where people get caught out most often. Your exhaust must not exceed 74dB at the kerb, according to UK noise regulations. Aftermarket exhausts are legal if they’re properly fitted and not unreasonably loud, but a straight-pipe cat-delete setup will get you pulled in about 30 seconds on any decent-sized town centre cruise. Brands like Cobra Sport or Milltek offer systems that sound proper without making you sound like you’ve removed the engine mounts as well.

    Cosmetic Mods

    Tints, spoilers, splitters, side skirts, diffusers. All legal, with caveats. Window tint must let through at least 75% of light on the front windscreen and 70% on the front side windows. Aero parts must be securely fitted and not create a hazard to other road users. Sharp edges on badly fitted carbon splitters have actually resulted in MOT failures, so fit it properly or don’t bother.

    Aftermarket exhaust system close-up as part of a legal UK car modification build
    Aftermarket exhaust system close-up as part of a legal UK car modification build

    What Will Actually Get You Pulled (and Possibly Nicked)

    Straight talk: these are the things that put you on the police radar fastest.

    • Excessively loud exhausts. You will get a noise abatement notice or a vehicle defect rectification notice. Guaranteed.
    • Illegal tints on front windows. Easy to spot, easy to issue a fixed penalty for.
    • HID or LED headlight conversions without the correct beam pattern. Blinding oncoming drivers is taken seriously. If your headlights aren’t type-approved for your vehicle, they’re illegal full stop.
    • Neon underbody lights. Still technically illegal on public roads in the UK. Save them for the show and shine.
    • Raised or excessively lowered ride height that affects handling. MOT testers and police alike can fail or seize a car they deem unsafe.

    Check the GOV.UK vehicle approval overview if you want the official breakdown of what requires formal approval before it hits your car.

    How to Build a Decent Modified Setup on a Budget

    You don’t need a £20,000 build fund to have a car that turns heads at a cruise meet. Honestly. Here’s how to think about it properly.

    Start With the Fundamentals

    Wheels, suspension, and a tidy interior will do more for your car’s image than a questionable big wing that wobbles at 40mph. A set of decent second-hand alloys from a well-known fitment can be had for £300-£500 if you shop around on forums like SELOC, WSCC, or the dedicated Facebook groups for your specific car. Refurbing them yourself costs next to nothing if you’re patient and have access to a spray can and some wet-and-dry paper.

    Buy Quality Where It Counts

    Cheap coilovers will destroy your car’s handling and your back. Spend a bit more on something from a recognised brand, even if you have to save for an extra month. The same goes for brakes. Braided brake lines and quality pads from EBC or Mintex are affordable upgrades that make a real difference and won’t land you in trouble on an MOT ramp.

    Prioritise Mods That Don’t Affect Your Insurance Bracket Too Much

    This is a big one. Cosmetic mods often have a lower insurance impact than performance ones. Adding 30bhp to a 1.6 as a 19-year-old with two years of no-claims is a recipe for a premium that costs more than the car. Always declare your modifications to your insurer. Not doing so can void your entire policy, leaving you uninsured and in serious trouble if you’re involved in an incident.

    The MOT: Your First Real Test

    Every modified car eventually faces the MOT, and that’s where dreams go to die if you haven’t built sensibly. Emissions, lighting, tyres, bodywork, noise, and ride height are all assessed. A good rule of thumb is to think about every mod you make in terms of whether a tester could reasonably fail it. If the answer is yes and you can’t be bothered fixing it, don’t fit it. The MOT fee alone hurts enough without a string of advisories and a fail on top.

    Knowing how to modify your car legally UK isn’t about limiting yourself. It’s about being smart enough to build something that actually lasts, passes its checks, and still absolutely smashes it at a cruise night without the added stress of flashing blues in your mirrors.

    Final Word: Build Smart, Stay Legit

    The culture around modified cars in the UK is one of the best in the world. The meets, the community, the knowledge people carry about their builds. But the quickest way to ruin your involvement in it is to get your car seized or rack up points because you couldn’t be bothered doing it properly. Take your time, do the research, buy quality, and declare everything to your insurer. Your future self, still with a driving licence and a car that runs, will thank you for it.

    Frequently Asked Questions

    What modifications are legal on a car in the UK?

    Most cosmetic mods like alloy wheels, spoilers, and tints are legal if fitted correctly and within the specified limits. Performance mods such as exhausts and suspension changes are also legal provided they don’t make the car unsafe, too loud, or fail MOT standards. Always declare any changes to your insurer.

    Do I need to tell the DVLA if I modify my car?

    You must inform the DVLA if modifications change the car’s appearance significantly or alter its technical specs, such as engine swaps. Cosmetic changes like alloys or body kits typically don’t require DVLA notification, but you should always inform your insurance provider regardless.

    Will modifying my car increase my insurance premium?

    Yes, in most cases modifications will increase your premium, particularly performance upgrades. Always declare every modification to your insurer honestly, as failing to do so can invalidate your policy entirely and leave you uninsured if you make a claim.

    What modifications will fail an MOT in the UK?

    Illegal window tints on front windows, excessively lowered suspension causing tyre rub, non-compliant lighting, and exhausts that fail the noise or emissions test can all fail an MOT. Any modification that makes the vehicle unsafe or non-compliant with UK road standards is grounds for a fail.

    Can police seize a modified car in the UK?

    Yes. Under the Road Traffic Act 1988, police can issue a Section 59 warning for antisocial use of a vehicle, and a second offence within 12 months can result in seizure. They can also prohibit a vehicle on the spot if modifications make it unsafe or unroadworthy.